Having a higher credit score tends to unlock better financial products and lower interest rates. But what if your FICO score is currently in the fair (580–669) or poor (300–579) range?
The good news is you still have solid options. Certain lenders specialize in serving applicants with poor or fair credit, offering personal loans that you can use for everything from debt consolidation and home repairs to medical bills and other unexpected costs. The key is knowing where to look and what trade-offs you will need to make.
Top Personal Loan Lenders for Lower Credit
These lenders stand out for their flexibility and willingness to work with low credit scores. We have categorized them based on their most notable benefit.
| Lender | Best for | Min. credit score/history | Loan amounts | APR range (fixed) |
|---|---|---|---|---|
| Upstart | Lowest minimum score | 300 (or no credit history) | $1,000 to $75,000 | 6.5% to 35.99% |
| OneMain Financial | Flexible terms and secured options | No minimum | $1,500 to $20,000 | 18.00% to 35.99% |
| Avant | Quick funding** | Poor/fair | $2,000 to $35,000 | 9.95% to 35.99% |
| Universal Credit | Entrepreneur loans | 560 | $1,000 to $50,000 | 11.69% to 35.99% |
| Oportun | Small loan amounts | No credit history required | $300 to $10,000 | Up to 35.99% |
*APR and fees are subject to change and depend on your specific financial situation.
**Funding is often available as soon as the next business day after approval.
Lender Spotlights
Here is a more detailed look at some of the best lenders that provide flexible personal loans if you have fair, poor, or no credit history.
1. Upstart: For poor or non-existent credit
Upstart uses an AI-driven lending model that looks beyond the traditional FICO score. It analyzes factors such as your education, employment history, and income, making personal loans accessible to those with a score as low as 300 or no credit history at all.
- Key benefit: Approves borrowers with little to no credit history
- Loan details: Offers loans from $1,000 up to $75,000 with terms of 36 or 60 months
- Fee note: Be aware of a high maximum origination fee (up to 12%) that Upstart deducts from your loan proceeds
2. OneMain Financial: Best for secured options
OneMain Financial is ideal if you need a lower interest rate and can offer collateral (such as a vehicle). This reduces the lender’s risk, increasing your odds of approval and potentially lowering your rate.
- Key benefit: Options for a secured loan and co-applicants
- Flexibility: Ability to choose your monthly payment due date, which helps with budgeting
- Eligibility: No early payoff penalties, but origination fees apply and vary by state
3. Avant: For speed and reliability
If you need quick funds, Avant offers a streamlined online process often leading to next-day funding upon approval.
- Key benefit: Quick application and fast fund disbursement
- Borrowing: Loans range from $2,000 to $35,000
- Flexibility: Provides a generous 10-day grace period before applying a late fee and may offer temporary interest rate reductions during a qualifying financial hardship
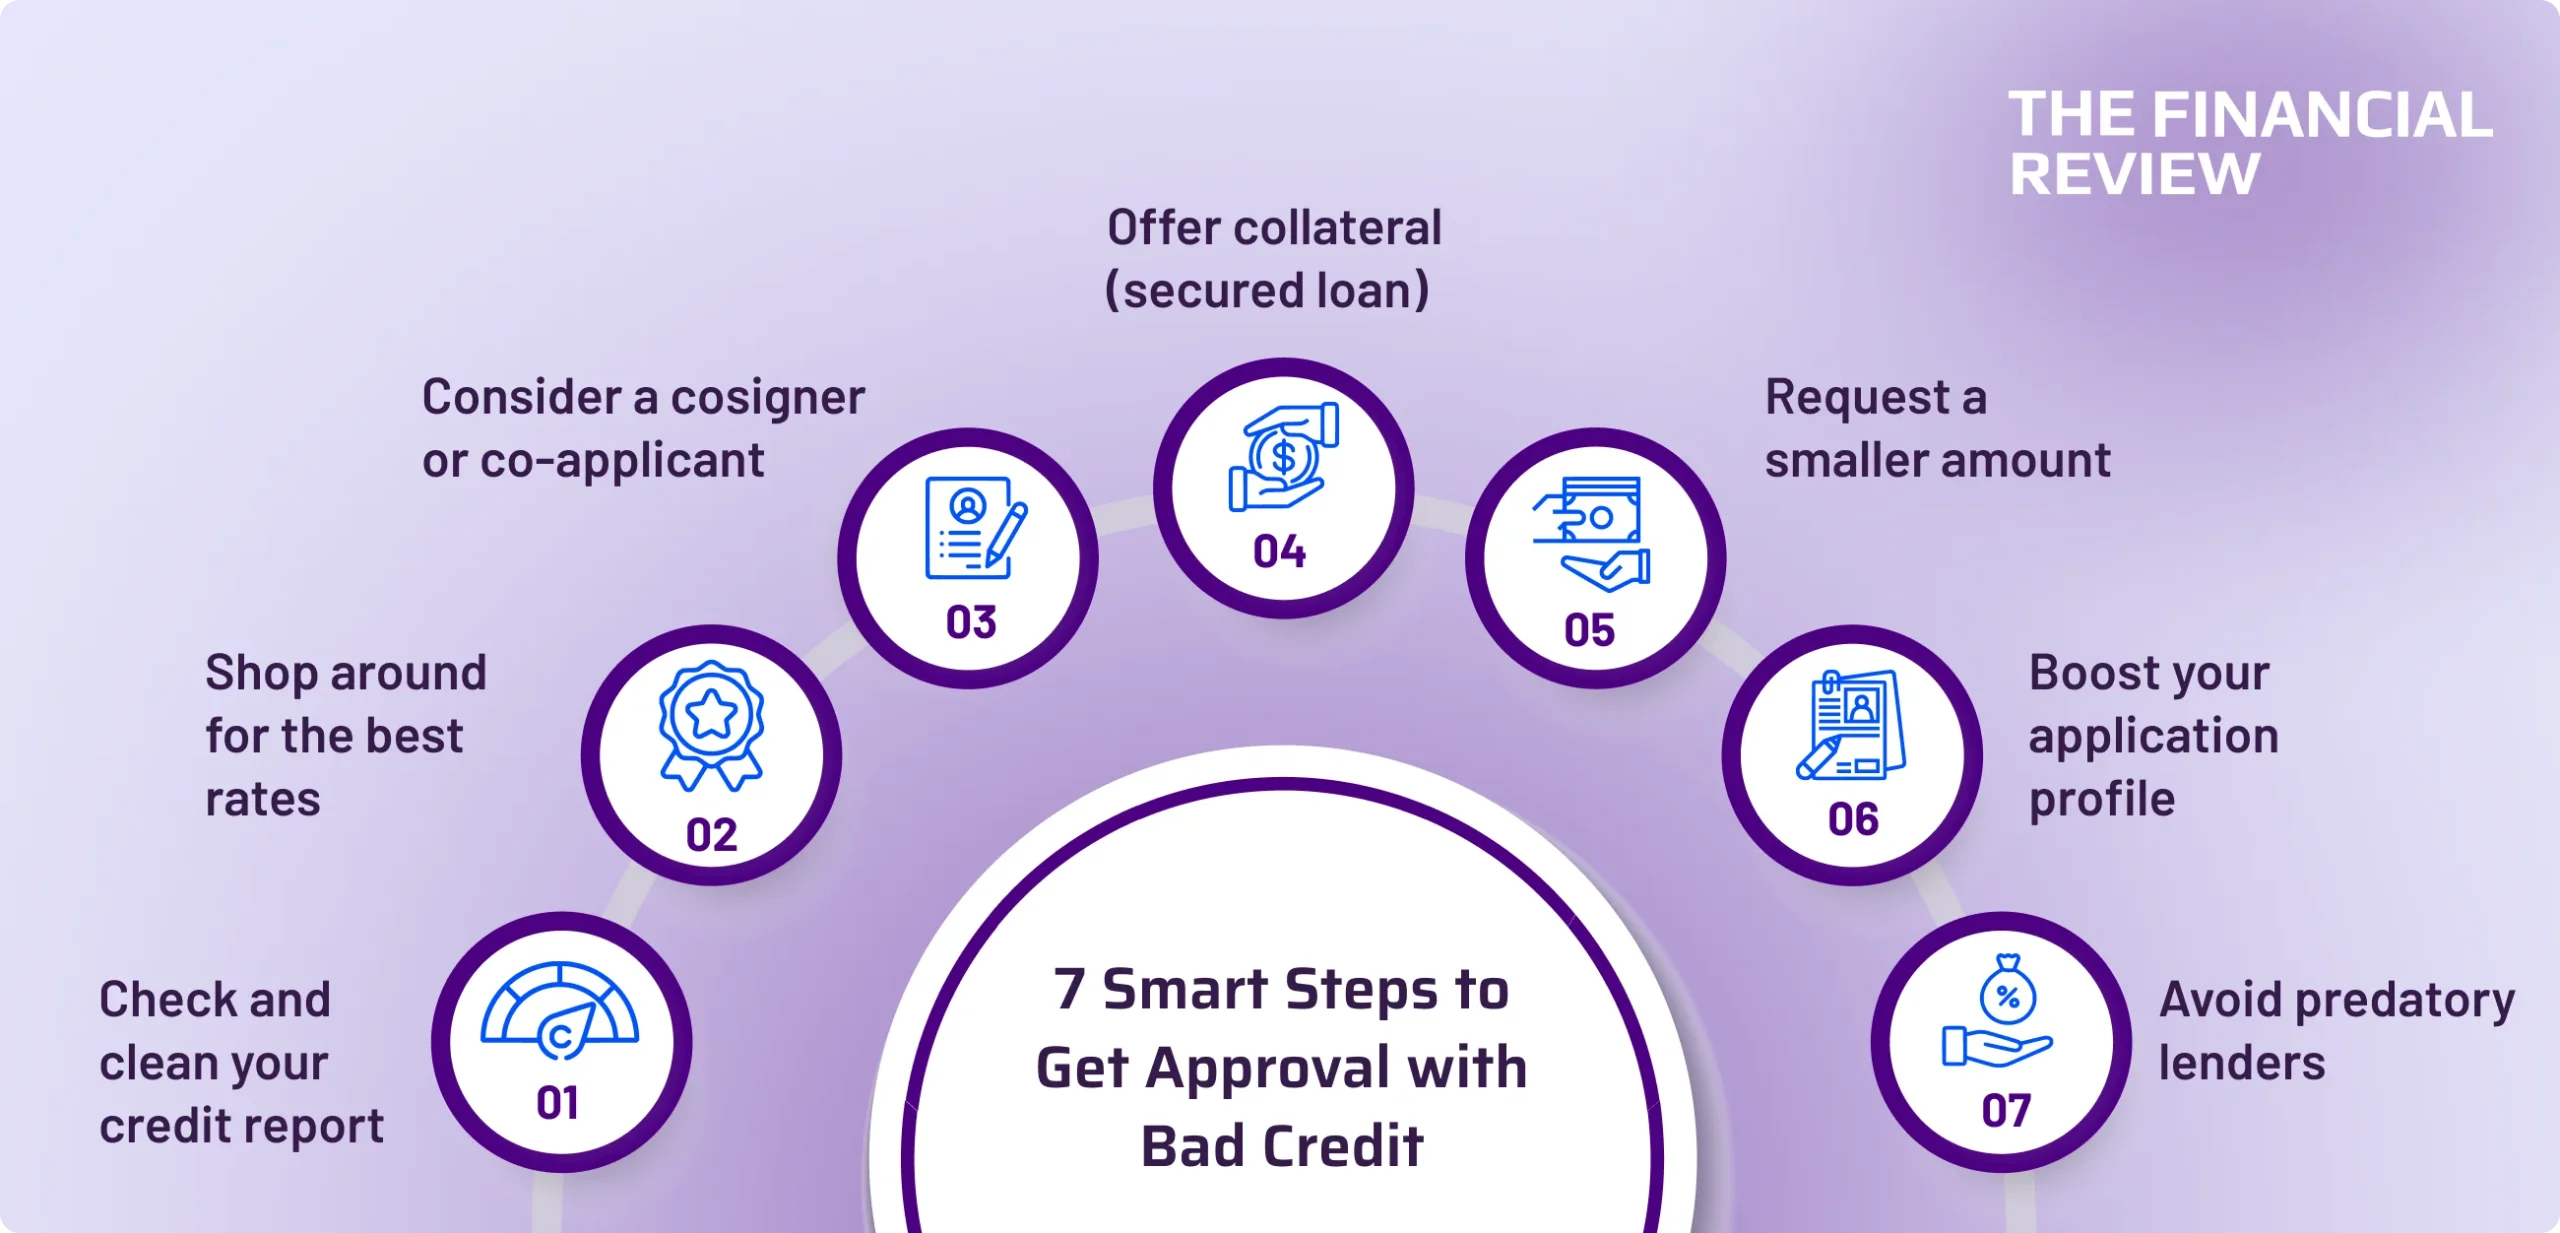
7 Smart Steps to Get Approval with Bad Credit
Getting a loan with poor credit requires more preparation than simply filling out a form. Following these steps can improve your chances and help you secure the most favorable terms.
Step 1
Check and clean your credit report
Before applying anywhere, pull your reports from all three bureaus (Experian, Equifax, and TransUnion). Dispute any errors, inaccuracies, or signs of fraud immediately. Removing old or incorrect entries can often provide a quick boost to your score.
Step 2
Shop around for the best rates
Avoid getting a “hard inquiry” — which can lower your credit score — before settling on a lender. Use prequalification forms from lenders or platforms such as Upstart to view estimated rates without impacting your credit. This is the smart way to compare offers.
Step 3
Consider a cosigner or co-applicant
Applying with a creditworthy person (a cosigner or co-applicant) who legally agrees to repay the debt if you cannot will significantly improve your approval odds and likely lead to a much lower interest rate.
Step 4
Offer collateral (secured loan)
A secured loan — backed by an asset such as a car or savings account — poses less risk to the lender. If your credit is weak, this is often the easiest path to approval and offers better rates than an unsecured loan.
Step 5
Request a smaller amount
Lenders are more willing to approve smaller loans for borrowers with low scores. If possible, start small to build a positive repayment history, then aim for a larger loan later.
Step 6
Boost your application profile
Lenders evaluate more than just your score. Present proof of stable income and a solid job history, and be ready to explain any specific credit issues (such as medical debt). Demonstrating a low debt-to-income ratio is always a plus.
Step 7
Avoid predatory lenders
Steer clear of short-term, high-cost options such as payday loans and title loans. These can have astronomical APRs (often 300% to 400% or more) and can quickly trap you in a cycle of worsening debt.
A Strong Step Forward
Securing a personal loan with fair credit is not an endpoint — you should view it as a powerful opportunity for financial repair.
While you will likely encounter higher APRs and origination fees than borrowers with perfect credit, the strategic advantage lies in choosing a loan with a fixed, predictable payment that fits your budget. Every on-time payment you make on this new debt is a direct investment in your credit future.
By diligently following the strategies outlined here — prequalifying, comparing the APR, and avoiding predatory debt — you can successfully navigate the low-score lending market, gain the funds you need, and actively build a credit history that will unlock better rates next time.
About the TFR Team
The TFR Team is a group of seasoned financial experts dedicated to delivering clear, insightful analysis and commentary on personal finance, investing, and market trends. With years of combined industry experience, the team brings trusted knowledge and practical perspectives to help readers make informed financial decisions.
Insights & Playbooks
The Financial Review - Fresh Insights Every Month
Expert reviews, step-by-step playbooks, and market explainers to help you make smarter money moves.