BriteCo: Top Pick for Jewelry Insurance
Pros
- The easy online process provides a quote in seconds and a policy in minutes.
- Customers can save up to 40% compared to homeowners riders and other specialized insurance competitors.
- Zero deductibles means there are no out-of-pocket expenses.
- BriteCo does not report jewelry claims to data services, which means there’s no impact on your homeowners policy.
- The claims process is fast and attentive.
Cons
- Customers may require an appraisal or detailed sales receipt to insure items.
- Policies cover replacement or repair only unless otherwise stated.
BriteCo summary
BriteCo is a specialty jewelry insurance provider known for its exceptional worldwide coverage at lower prices compared to other specialty jewelry insurance providers and homeowners’ riders or floaters. BriteCo jewelry insurance policies have zero deductibles, so you don’t have to worry about paying anything out-of-pocket to replace a lost or stolen piece.
BriteCo’s 125% replacement coverage also gives you extra protection in case your insured item increases in value over time — especially important with current gold prices. If you need to file a claim, BriteCo will work with the jeweler of your choice for a replacement or repair and assign a representative to help you through each step of the process.
Another advantage over homeowners or renters insurance coverage is that BriteCo does not report jewelry claims to data services that other providers often use to assess risk. This means making a jewelry claim will not raise your homeowners or renters premiums or risk cancellation of your policy. That is significant protection for homeowners who are facing double-digit increases in their homeowners insurance premiums.
It is worth getting a quote from BriteCo to compare with your other options.
CHUBB: Preferred for High-End Jewelry
Pros
- CHUBB is an established, high-end property and casualty insurance company that offers a multitude of insurance lines for classic cars, yachts, art, and jewelry.
- Customers only require appraisals for jewelry items exceeding $100,000 in value.
- The company is a preferred choice for high-wealth individuals with substantial and valuable collections.
Cons
- Customers must go through an agent to get a policy, making it difficult to shop individually.
- High-value items — (usually over $100,000 — require appraisals.
- Policies have some of the highest premium costs compared to other specialized insurance providers.
CHUBB summary
CHUBB insures luxury jewelry and collectibles, catering to high-net-worth clients who expect policies tailored to their specific needs. CHUBB policies offer worldwide coverage with no deductibles for most jewelry losses, as well as an agreed value option that pays 100% of insured value on covered total losses. However, premiums can be significantly higher than competitors.
Lavalier: Good for Less Expensive Jewelry
Pros
- Unscheduled items valued less than $1,000 do not require an appraisal.
- The choice of deductible can help offset annual insurance premium costs.
- Both annual and installment payment options are available.
Cons
- Scheduled jewelry insurance policies are limited to $50,000 per item.
- Policies exclude men’s and women’s watches, with a few exceptions.
- Other exclusions to coverage apply, so be sure you know exactly what your policy covers.
Lavalier summary
Lavalier is one of the few jewelry insurance providers to offer customers an option to purchase non-scheduled jewelry coverage with an agreed value of less than $1,000 without requiring an appraisal. This may be the best insurance choice for people with heirloom or vintage jewelry pieces that have more sentimental value than actual cash value. For other luxury jewelry items or vintage pieces in pristine condition, Lavalier offers scheduled jewelry insurance policies limited to $50,000 per item. Coverage exclusions apply, but Lavalier’s all-risk coverage includes major perils, such as loss, theft, damage, and mysterious disappearance.
The Financial Review has evaluated coverage from some of the top specialty insurance companies that focus on jewelry. The jewelry insurance providers here all cover loss, theft, damage, and mysterious disappearance. This is important since most standard homeowners policies typically do not cover mysterious disappearance — i.e., loss without a clear explanation.
Frequently Asked Questions
Is it worth insuring jewelry?
Yes. Jewelry insurance is an affordable option — annual premiums typically cost just 1%–2% of your item’s value — and it provides total peace of mind for your most precious valuables. This comprehensive coverage protects you from theft, damage, loss, and mysterious disappearance, ensuring that if you need to make a claim, there will be little to no out-of-pocket cost.
What does jewelry insurance not cover?
While specialty jewelry insurance coverage protects against loss, theft, damage, and mysterious disappearance, it typically does not cover intentional damage, damage from natural disasters, or damage sustained during military action.
What proof do I need for jewelry insurance?
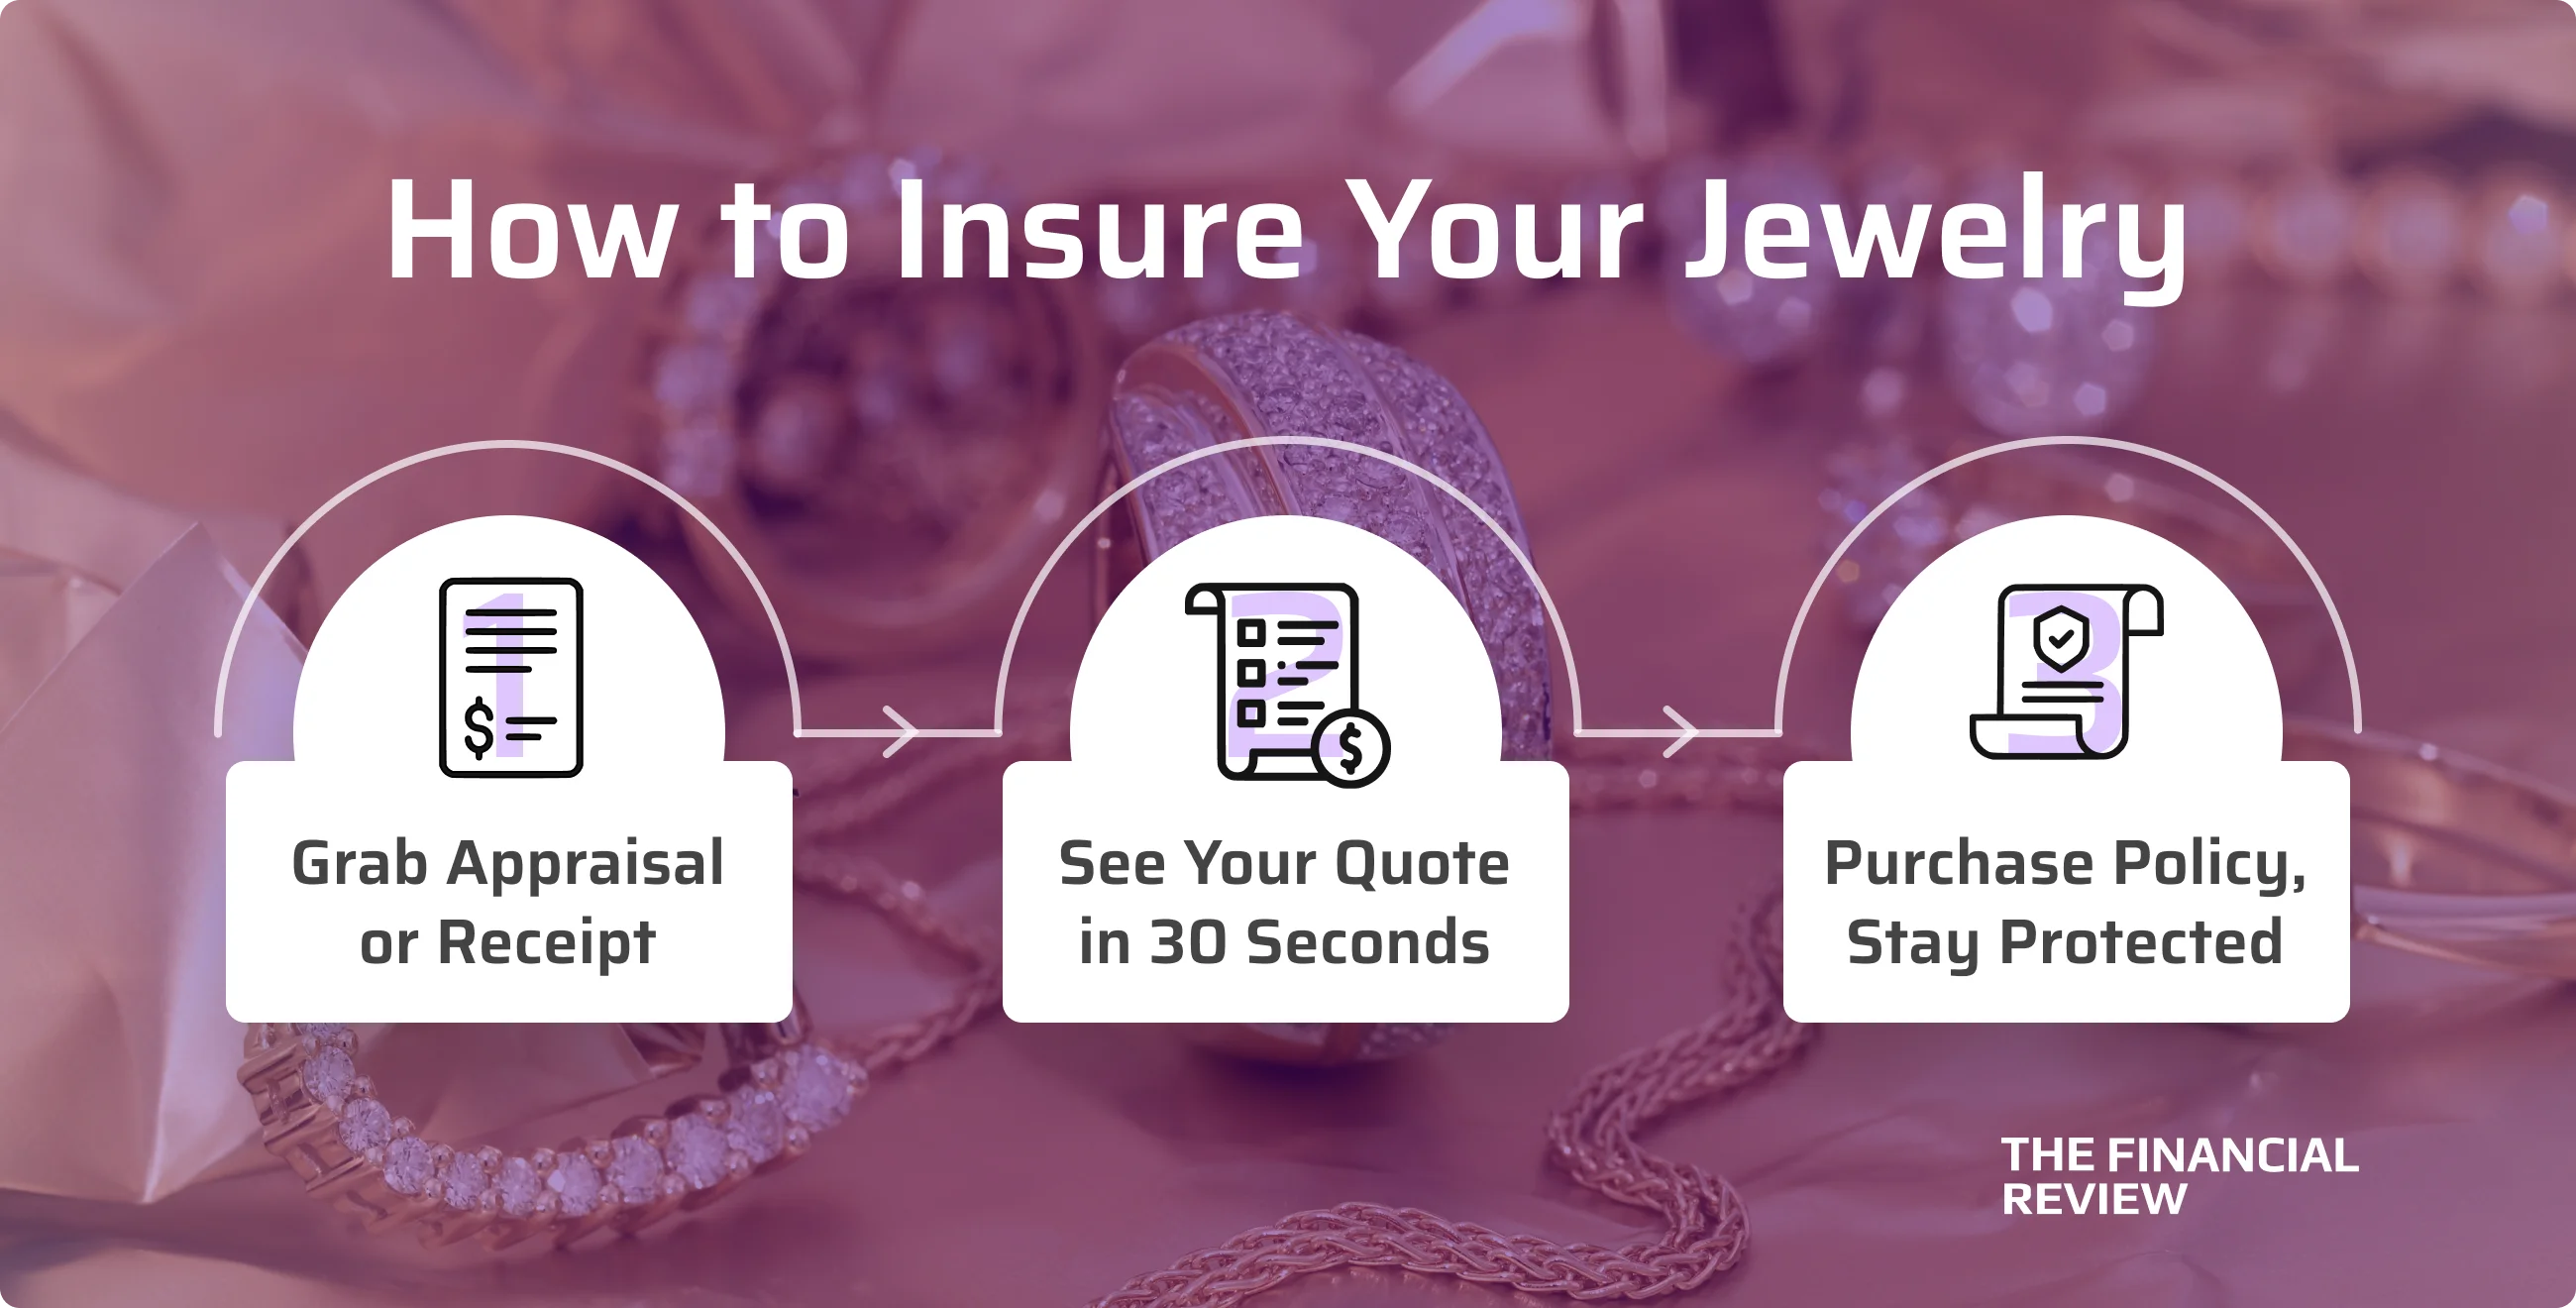
To secure a policy, you will typically need a professional appraisal and/or detailed sales receipt and lab certificate if available, along with photos and additional details. An appraisal ensures there is documentation of the item’s current market value.
What happens if you lose your insured engagement ring?
If you have a policy that covers loss or mysterious disappearance, you can file a claim to get a replacement item.
Do I need an appraisal or receipts to insure jewelry?
In most cases, yes. Most jewelry insurance companies will specify that you need an appraisal of your fine jewelry or engagement ring to apply for insurance. A receipt helps support the valuation.
Is my jewelry covered by homeowners or renters insurance, or do I need a separate policy/rider?
Standard homeowners or renters policies may offer limited coverage — often $1,000–$2,000 maximum — and usually will not cover loss, damage, disappearance, or theft that happens outside your home. In contrast, specialty jewelry insurance provides broader coverage and protection.
How much does jewelry insurance cost per year?
Typical premiums cost about 1%–2% of the appraised value of the item per year. For example, a $10,000 piece might cost $50–$150 annually to insure.
About the TFR Team
The TFR Team is a group of seasoned financial experts dedicated to delivering clear, insightful analysis and commentary on personal finance, investing, and market trends. With years of combined industry experience, the team brings trusted knowledge and practical perspectives to help readers make informed financial decisions.
Insights & Playbooks
The Financial Review - Fresh Insights Every Month
Expert reviews, step-by-step playbooks, and market explainers to help you make smarter money moves.